Author: admin_lant

  • OPCF 19 Explained: Why OPCF 19A Is Ontario’s Agreed Value Endorsement

    OPCF 19 Explained: Why OPCF 19A Is Ontario’s Agreed Value Endorsement

    The names OPCF 19 and OPCF 19A look almost the same, but they do very different jobs. That single letter matters when you insure a classic, collector, restored or modified vehicle in Ontario.

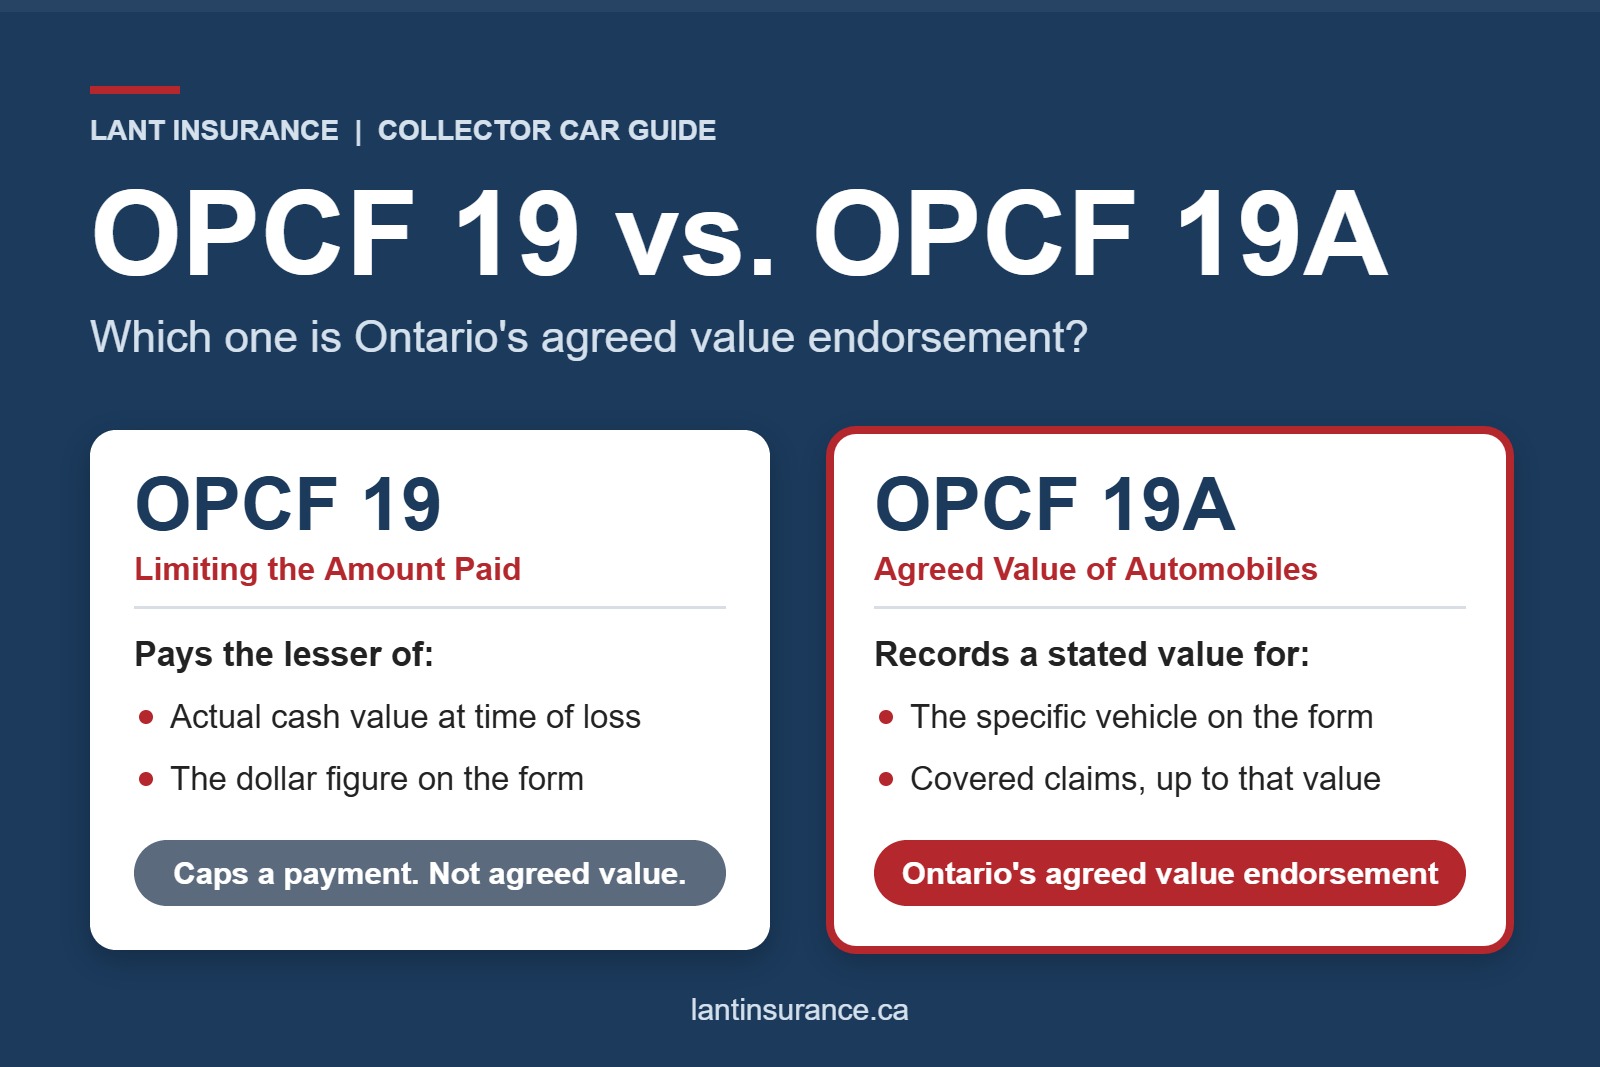
    Here is the key point: OPCF 19 is a limiting endorsement, not an agreed value endorsement. Ontario’s regulator lists OPCF 19 as Limiting the Amount Paid for Loss or Damage Coverages and OPCF 19A as Agreed Value of Automobiles in its list of approved policy change forms. The current OPCF 19A form says its purpose is an arrangement about the value of the automobile.

    So if you want the value of a special vehicle agreed before a covered loss, ask about OPCF 19A, not just “OPCF 19.” This guide explains the difference in plain language, how a normal Ontario policy settles a claim, and what to check before you rely on an agreed amount.

    The quick answer: OPCF 19 does not create agreed value

    What OPCF 19 is designed to do

    OPCF 19 is titled Limiting the Amount Paid for Loss or Damage Coverages. It caps what the insurer will pay under Section 7, the optional Loss or Damage section of an Ontario auto policy.

    The form’s own wording makes the effect clear. You agree that the insurer will not pay more than the actual cash value at the time of the loss, or the dollar figure written on the form, whichever is less. The coverage is still subject to the deductible on your Certificate of Automobile Insurance.

    Read that again, because it is the opposite of what many people expect. OPCF 19 cannot pay you more than actual cash value. It can only pay less. It does not set a protected value for a special vehicle.

    What OPCF 19A is designed to do

    OPCF 19A is the form called Agreed Value of Automobiles. It records the value of the specific automobile shown on the form. In certain circumstances the insurer agrees to pay that amount and gives up its right to pay actual cash value instead.

    The form replaces section 7.7 of the Ontario Automobile Policy, “What We Will Pay,” for the vehicle listed. That is why OPCF 19A matters for a collector car. It puts a stated value on the policy before a covered loss, instead of leaving the value to be argued after one, and it is the mechanism behind most agreed-value collector car coverage written in Ontario.

    Why the difference matters

    Calling OPCF 19 an “agreed value endorsement” can lead to a serious misunderstanding. One form limits what may be paid. The other changes how the car is valued. Before you buy or renew, check the form number and title on the paperwork, not just a verbal description.

    How a standard Ontario policy values vehicle damage

    Section 7 coverage is optional

    Ontario’s standard owner’s policy, the Ontario Automobile Policy (OAP 1), treats Section 7 as optional coverage for loss of or damage to your own car from collision, fire, theft and other insured risks. You only have a particular coverage when it is shown on your Certificate of Automobile Insurance. See the current OAP 1, approved for use on or after July 1, 2026.

    This matters because agreed value is not a stand-alone promise to pay for every kind of damage. OPCF 19A works with the Loss or Damage coverage you actually bought, whether that sits on a collector policy or on the everyday auto insurance covering the car in the other half of the garage. The loss still has to come from a peril your policy covers.

    Actual cash value and depreciation

    Without an agreed value endorsement, section 7.7 of the OAP 1 says the insurer will not pay more than the car’s actual cash value at the time it was damaged or stolen, less the deductible. The value is worked out after taking depreciation into account, and the insurer pays the lower of the repair cost or the actual cash value. Ontario’s statutory conditions for automobile insurance follow the same principle.

    Actual cash value is not the original purchase price, and it is not the total you have spent. It is a valuation as at the moment of the loss. For an ordinary daily driver that is often a sensible approach. For a carefully restored or rare car, an owner may worry that a post-loss valuation will not reflect documented restoration work, rarity or condition.

    A collector car does not get agreed value automatically

    Owning an antique or collector vehicle does not create an agreed value settlement on its own. A car can be old, rare and expensive to restore and still be settled under the normal actual cash value rule, unless the policy says otherwise. The certificate, the endorsements and the insurer’s current wording are what count.

    A historic vehicle plate does not change this either. It is a registration status, not an insurance policy, as we explain in our guide to historic vehicle plates in Ontario and what they mean for your coverage.

    If the two valuation methods are still blurring together, our guide to agreed value versus actual cash value walks through what each one pays out on a real claim.

    How OPCF 19A agreed value works

    The stated amount is tied to one specific vehicle

    The OPCF 19A form identifies the automobile by model year, make and model, and serial number or VIN. It then shows a value, including taxes where they apply. The insurer agrees to pay up to that value under Section 7 when loss or damage is caused by a peril you are insured against.

    So the agreed amount must be attached to the right car. Check the year, make, model and VIN as well as the figure. Do not assume that a recent appraisal, a photo folder or a stack of restoration invoices has changed anything, unless the insurer has actually issued the endorsement or another written policy change.

    “Up to” does not mean every claim pays the full amount

    Agreed value does not mean that every small or medium repair produces a payment for the whole figure on the form. The wording says the insurer will pay up to the stated value. For a repairable loss, the repair cost can be far below that ceiling.

    The form also says the insurer will not pay more to repair the car than the value shown. And the OAP 1 keeps the insurer’s right to repair, replace or rebuild in appropriate circumstances. OPCF 19A changes the valuation rule in section 7.7. It does not remove the rest of the policy. The form states that all other terms and conditions stay the same.

    There is a useful clause about parts

    One line in OPCF 19A is worth knowing if you own something rare. If a part needed to repair the car is no longer available, the form says the insurer will pay an amount equal to the manufacturer’s latest list price for that part.

    That does not solve every sourcing problem, but it is a real provision, and it is one more reason to read the form itself rather than a summary of it.

    Deductibles still apply

    OPCF 19A does not erase your deductible. The form says the coverage is subject to the loss or damage deductibles shown on the Certificate of Automobile Insurance. If the stated value is $75,000 and a covered total loss is settled under Section 7 with a $1,000 deductible, that deductible is still part of the calculation.

    Ask whether the amount on the form includes applicable taxes, and confirm the deductible for each relevant coverage. A clear answer before a loss is much easier than a dispute after one.

    A simple comparison

    Normal OAP 1 section 7.7. Uses actual cash value, after depreciation. Pays the lower of the repair cost or the actual cash value, less the deductible.

    OPCF 19. Pays the lower of actual cash value or the figure written on the form, less the deductible. It caps the payment; it does not protect a value.

    OPCF 19A. Sets an agreed value for the listed automobile for certain covered Section 7 claims, subject to the form wording and the applicable deductibles.

    What happens when another driver is at fault

    Direct Compensation – Property Damage changes the claim path

    In Ontario, a collision with another insured Ontario vehicle can be handled under Direct Compensation – Property Damage (DCPD) coverage. The OAP 1 says this coverage may pay for damage to your car when you or your driver were not entirely at fault, subject to the policy conditions. The standard policy uses actual cash value for this type of claim. None of this crosses provincial lines, so if you are pricing or garaging a car in Quebec, the forms and the fault rules behind car insurance costs in Montreal work on a different system and an Ontario endorsement will not follow the vehicle there.

    Do not assume that “the other driver was at fault” makes the valuation question disappear. The coverage section, the degree of fault, the deductibles and the endorsements all affect how the loss is handled. Ontario drivers can also opt out of claiming under DCPD using OPCF 49, and that choice matters here, as the next section explains.

    OPCF 19A can cover a shortfall in limited circumstances

    The current OPCF 19A form has a specific DCPD provision. Where the amount payable under DCPD is less than what would have been payable under the agreed value section, the insurer will pay the difference. But three conditions apply:

    1. you must not have elected out of recovering damages under DCPD;
    2. you must have purchased All Perils or Collision or Upset coverage; and
    3. the amount paid does not include the DCPD deductible that applies to the claim.

    This is technical, but it is important. It is a good reason to review the whole coverage package rather than looking only at the agreed value figure.

    Why agreed value matters for classic and restored cars

    The value may not follow ordinary depreciation

    An older car can gain value after a careful restoration. A rare or limited-production vehicle may never follow a standard depreciation curve at all. An agreed value discussion lets the owner and the insurer settle the value question before a covered loss, rather than debating it once the car is damaged or stolen.

    That does not mean every vehicle needs OPCF 19A. The right fit depends on the car, how it is used, what the insurer offers and the value you can support with evidence.

    Keep the supporting records current

    Good records make a value discussion much easier. Keep clear photos, restoration invoices, purchase documents, parts receipts and any appraisal the insurer asks for — our five tips for getting an accurate appraisal on your classic car cover the documentation a valuer will expect to see. If you finish a major restoration, add expensive modifications or see a real change in market value, speak to your broker before the next renewal.

    The form, not your own estimate, is the agreement. Make sure the policy reflects the value you and the insurer have accepted.

    How to set up or review agreed value coverage
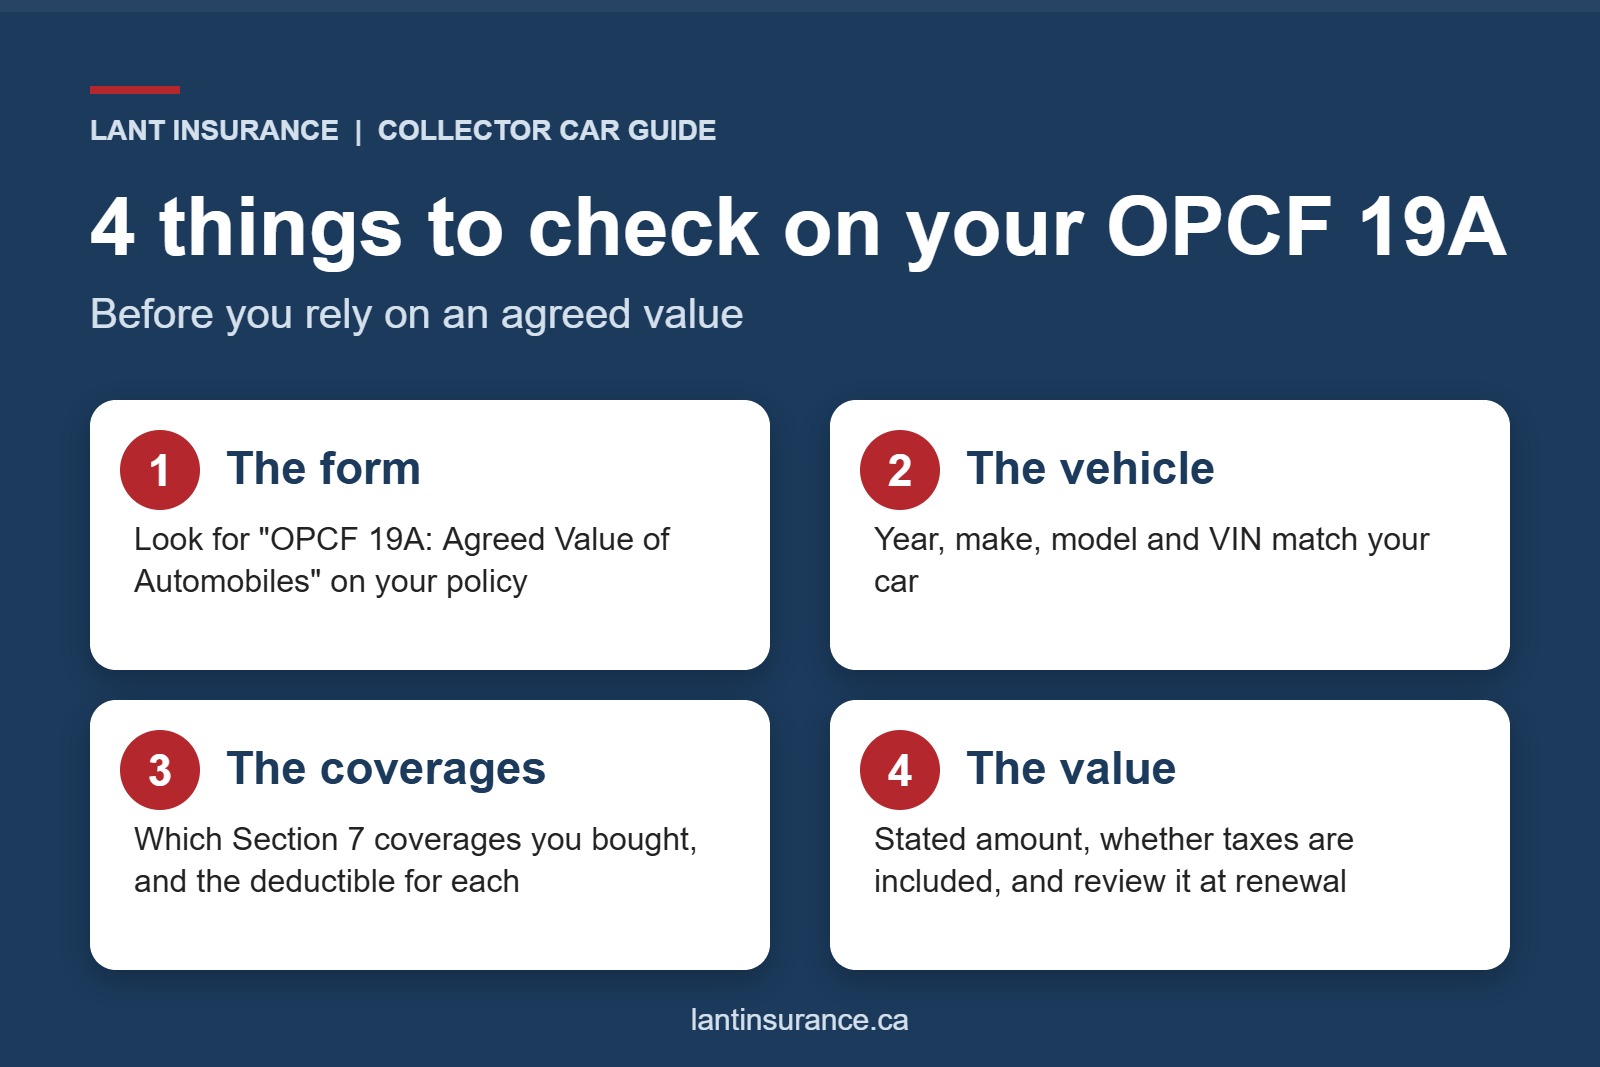
    Checklist of four things to check on an OPCF 19A endorsement: the form, the vehicle, the coverages and deductibles, and the stated value

    1. Check the certificate and endorsements

    Look for the exact wording OPCF 19A: Agreed Value of Automobiles. Confirm that the vehicle is correctly identified and that the stated value is visible. If all you can find is an appraisal in your own file, ask whether an endorsement was ever issued.

    2. Check the physical damage coverages

    Ask which Section 7 coverages are on the car: Collision or Upset, Comprehensive, Specified Perils or All Perils. Agreed value does not create coverage for a peril you did not buy. Confirm the deductible for each coverage as well.

    3. Ask how the value was set and what it includes

    Ask whether the amount includes applicable taxes, documented restoration work and the equipment or modifications that matter to you. The OAP 1 has separate limits for some electronic accessories and equipment, so it is wise to ask how non-factory items are treated under your policy.

    4. Review the amount after any meaningful change

    Review the stated value at renewal, and sooner if the car changes materially. A new engine, a completed restoration, a major repair, newly installed equipment or a big market shift can all make an old figure less useful. The start of show season is a natural prompt, so check the stated value while you are running through the rest of your pre-show insurance checklist. Do not wait for a claim to find out that the agreed amount is out of date.

    Do not confuse OPCF 19A with OPCF 43

    OPCF 43 is another Ontario endorsement that causes confusion. FSRA describes it as Removing Depreciation Deduction in the event of a total loss. It is not the agreed value form. See FSRA’s OPCF 43 page for its current purpose.

    The names sound related because both affect claim valuation, but they answer different questions. One removes a depreciation deduction in the circumstances set out in its own wording. The other records an agreed value for a listed automobile. They are not substitutes for each other.

    Questions to ask before you rely on an agreed value

    Before you insure or renew a special vehicle, ask these in writing:

    1. Does my policy include OPCF 19A, and which automobile does it apply to?
    2. What value is shown, and does it include applicable taxes?
    3. Which loss or damage coverages and deductibles apply to this vehicle?
    4. How would a not-at-fault collision be handled under DCPD and OPCF 19A?
    5. How are custom parts, restoration work and non-factory equipment treated?
    6. When should the agreed value be reviewed or updated?

    For an everyday vehicle, you can also review our auto insurance options to make sure the coverage matches how the car is really used.

    Conclusion

    OPCF 19 and OPCF 19A should never be treated as the same thing. OPCF 19 caps a Section 7 payment at the lower of actual cash value or a stated figure. OPCF 19A is Ontario’s agreed value endorsement.

    For a collector, classic, restored or modified car, that difference can be expensive. Check that the correct form is on the policy, that the listed value is current, that the right physical damage coverages are in place, and that you understand the deductibles. If you would like help reviewing coverage for a special vehicle, talk to a broker at Lant Insurance. This article is general information only; your own policy wording, certificate, endorsements and claim facts govern.

    Frequently asked questions

    Is OPCF 19 an agreed value endorsement?

    No, OPCF 19 is a limiting endorsement, and it can only reduce what is paid. OPCF 19A is Ontario’s agreed value endorsement. Always check the form number and title on your policy rather than relying on a short verbal description.

    Does OPCF 19A guarantee the full stated value after every claim?

    No, the form says the insurer will pay up to the value shown, and it will not pay more than that value to repair the car. A smaller repair claim is settled for the covered repair cost, and the insurer keeps its policy rights to repair, replace or rebuild. The loss must also be caused by a peril you are insured against.

    Do I need Collision or Comprehensive coverage for OPCF 19A to matter?

    OPCF 19A works with your Section 7 Loss or Damage coverages; it does not add coverage for a peril you did not buy. Its DCPD difference provision applies only if you have purchased All Perils or Collision or Upset coverage. Ask your broker to confirm the full package.

    Does the deductible apply to an agreed value claim?

    Usually, yes the OPCF 19A form says the coverage is subject to the Section 7 deductibles shown on the Certificate of Automobile Insurance. Confirm the applicable deductible before you rely on the stated value.

    Does agreed value apply if another driver caused the collision?

    It can still be relevant because a not-at-fault Ontario collision may be handled through DCPD. OPCF 19A can pay the difference in limited circumstances, but only if you have not elected out of DCPD and you have bought All Perils or Collision or Upset coverage.

    Is OPCF 19A only for classic or collector cars?

    No, the form is not limited to classic vehicles. It may be considered for any automobile where the insurer agrees to a stated value. Whether it is available or suitable depends on the insurer’s underwriting rules and the car itself.

    Does an appraisal automatically give my vehicle agreed value coverage?

    No, an appraisal can support a value, but it does not change the insurance contract by itself. Check that OPCF 19A has been issued and that it lists the correct vehicle and the correct amount.

    What is the difference between OPCF 19A and OPCF 43?

    OPCF 19A is the agreed value endorsement for a listed automobile. OPCF 43 is a different endorsement that removes a depreciation deduction in the total loss circumstances set out in its own wording. They solve different problems and are not interchangeable.
  • Historic Vehicle Plates in Ontario and What They Mean for Your Coverage

    Historic Vehicle Plates in Ontario and What They Mean for Your Coverage

    An Ontario historic vehicle plate is more than a finishing touch for a well-kept classic. It is a special registration status, and it comes with rules about the vehicle itself and how you may use it on the road.

    The main point is simple. A historic plate is not an insurance policy. It does not set your claim value, it does not add physical damage protection, and it does not replace the need for valid auto insurance. Your plate and your policy need to tell the same honest story about the car, its condition and how you use it.

    This guide explains the difference in plain language, so you can enjoy your collector car without making assumptions that cause trouble later.

    Historic vehicle plate vs. auto insurance policy

    A historic vehicle plateAn auto insurance policy
    Is a provincial vehicle registration status.Is a contract that provides the insurance you bought.
    Is based on Ontario’s legal definition of a historic vehicle and its permitted use.Lists the insured vehicle, drivers, coverage choices, deductible and policy period.
    Does not decide how much an insurer will pay after a loss.Sets the coverage, limits, exclusions and claim settlement terms.
    Does not replace proof of insurance.Provides the proof of insurance you must carry while driving.

    Think of the plate as a registration class and the policy as your financial protection. Both matter, but they do different jobs.

    Ontario’s legal definition of a historic vehicle

    A historic vehicle must meet every part of the test

    Under Ontario Regulation 628, a historic vehicle is a motor vehicle that meets all of these conditions:

    • It is at least 30 years old.
    • It is driven on a highway in parades, for exhibition, on tours or at similar functions organized by a properly constituted automobile club, or for repair, testing or demonstration for sale.
    • It is substantially unchanged or unmodified from the original manufacturer’s product.
    • It does not have year-of-manufacture plates attached to it.

    Age is only one part of the test. A 30-year-old vehicle does not qualify just because it is old. Its use, its condition and its plates all matter too.

    Historic plates and year-of-manufacture plates are not the same

    Ontario also has a separate year-of-manufacture plate option for some qualifying vehicles. That is a different thing. The regulation states clearly that a historic vehicle does not have year-of-manufacture plates attached to it.

    If you are choosing between the two, do not decide on looks alone. Confirm which option fits the car’s condition and your intended use before you apply.

    Modifications can change the answer

    A classic with period-correct repairs is not the same as a heavily modified car. Engine swaps, major suspension changes, custom chassis work and other big alterations may affect whether the vehicle still meets the historic vehicle test. They can also matter to an insurer when it looks at the car’s value and risk.

    Keep clear records of restoration work, receipts, photographs and any major modification. Good records make your conversations with both ServiceOntario and your insurer much easier.

    How historic plate status affects the way you drive

    It is not a daily-driver registration class

    The legal definition links historic vehicle use to parades, exhibitions, club tours, repair, testing and demonstration for sale. It is not a general commuting class.

    A drive to a scheduled club tour, a car show or a repair shop fits those listed purposes far more easily than a school run or a weekly grocery trip. If a planned trip does not clearly fit, check the rule before you drive.

    Your insurance needs to match the real use

    Insurance questions are usually practical. How often do you drive the car? Where is it kept? Who drives it? Is it used for commuting, business, shows, club events or only the odd pleasure drive?

    Do not describe the car as a weekend collector vehicle if you actually use it for regular transport. The Financial Services Regulatory Authority of Ontario (FSRA) says policyholders must give true and accurate information and must report changes that could affect their insurance.

    That rule protects you as much as it protects the insurer. Correct details help make sure you are quoted for the right kind of policy, with no surprises during a claim.

    What a historic plate means for your coverage

    You still need valid Ontario auto insurance

    Ontario requires vehicle owners to carry auto insurance, and you must have proof of insurance while driving. FSRA explains that the Certificate of Automobile Insurance identifies the insured vehicles, the listed drivers, the coverages selected and the policy period. A vehicle is insured only when it is properly shown on that certificate. See FSRA’s guide to Ontario’s auto insurance requirement.

    A historic plate does not create insurance by itself. You still need an active policy for that specific car.

    The policy, not the plate, decides what is covered

    Your plate does not automatically include:

    • agreed value settlement;
    • Collision or Upset coverage;
    • Comprehensive coverage for theft, vandalism or weather damage;
    • coverage for spare parts, tools or automobilia;
    • roadside assistance or flatbed towing; or
    • coverage while the car is being restored, transported or stored.

    Some of these protections may be available through a collector car insurance policy or other optional coverage, but the wording and availability differ by insurer. Ask what is included rather than relying on the word “historic.”

    Ontario’s standard auto policy includes certain core coverages. Physical damage protections such as Specified Perils, Comprehensive, Collision or Upset, and All Perils are optional choices that deserve a careful read. FSRA’s guide to optional coverage explains the options and notes that deductibles and exclusions may apply.

    A historic plate does not guarantee agreed value

    Many collector car owners want to protect the car’s real market or restoration value. That is a valuation question, not a plate question.

    Ask your broker or insurer whether the policy uses actual cash value, agreed value or another settlement method. Then ask how the amount is supported, when it must be reviewed, and what happens after a partial loss or a total loss. In Ontario, the agreed value endorsement is OPCF 19A, and it must actually be issued for your vehicle. For a plain-English comparison, see our guide to agreed value vs. actual cash value.

    Accurate disclosure is essential

    Tell the insurer about the historic plate, the car’s current condition, any modifications, the annual kilometres, the storage location, the regular drivers and the intended use. Report changes too, such as finishing a restoration, adding performance parts or starting to drive the car more often.

    FSRA warns that incomplete or incorrect information can lead to a policy being cancelled or even treated as void, which can leave the owner without protection for a claim. Read FSRA’s advice on working with an insurer or broker before you make changes.

    Coverage questions collector car owners should ask

    How will the car be valued after a loss?

    Do not assume a classic will be valued like a modern used car. Ask how the insurer will set the value and which documents it wants: an appraisal, a purchase record, comparable sales, restoration invoices or photographs. Our tips for getting an accurate appraisal on your classic car cover what a good appraisal should include.

    If the value changes after major work, tell the insurer. An old appraisal may not reflect a finished restoration, a rare option or an expensive upgrade.

    Which physical damage coverages are included?

    Third-party liability coverage is essential, but it does not protect your own car. Ask whether the quote includes Comprehensive, Collision or Upset, Specified Perils or All Perils, and confirm the deductible for each one.

    Comprehensive can respond to certain losses other than collision, including theft, vandalism and falling objects, subject to the policy terms. Collision or Upset can respond when the car hits another object or tips over. Read the wording before you assume a particular loss is covered.

    What happens during storage, transport or restoration?

    Collector vehicles often spend long stretches in a garage, workshop or storage unit. They also travel on trailers to shows, appraisals and repair shops. Each situation raises its own questions:

    • Is the car covered while it is stored?
    • Is theft, fire or water damage included?
    • Are detached parts, tools and memorabilia covered, and up to what limit?
    • Is the car covered while it is being transported?
    • Does coverage change while it is partly dismantled or under restoration?

    There is no single answer for every policy. Get your answer in writing before you rely on it.

    Do the policy’s use limits fit your plans?

    Some collector car policies are built for limited pleasure use, events and occasional drives. If you want to commute, take frequent long trips, use the car for business or let a new driver use it regularly, say so before you buy or renew.

    For a car used as ordinary transport, review our auto insurance options as well. The right choice depends on how the car is actually used, not on its age or looks.

    The permit fee and the insurance premium are separate

    Ontario Regulation 628 currently lists a $0 annual permit validation fee for a historic vehicle permit in Schedule 4. That does not mean the car is insured for free, and it does not mean every registration transaction is free. Insurance premiums, deductibles and optional coverage are a separate matter.

    Before you apply, confirm the current process and any fees directly with ServiceOntario. Before you drive, confirm that the car appears correctly on your insurance certificate and that you have current proof of insurance.

    A simple checklist before you apply, renew or drive

    Confirm the vehicle qualifies

    • Check that the car is at least 30 years old.
    • Review whether it is still substantially unchanged or unmodified from the original manufacturer’s product.
    • Confirm that you are not using year-of-manufacture plates on it.
    • Make sure your intended road use fits the historic vehicle definition.

    Make the insurance details match

    • Tell the insurer that the car has, or will have, historic vehicle registration.
    • Describe the real use: club tours, exhibitions, repair trips, testing, pleasure drives or anything else you expect.
    • Disclose modifications, restoration status and any updated value.
    • Confirm the drivers, the estimated annual kilometres and the storage location.
    • Read the Certificate of Automobile Insurance and the policy wording, not just the quote summary.

    Keep useful documents together

    Keep your policy, proof of insurance, registration papers, photographs, invoices and appraisal in one place you can reach quickly. Update the file after a major restoration stage, a new appraisal or a change in use. It saves time at renewal, and it helps you explain the car accurately if you ever need to claim.

    Conclusion

    A historic vehicle plate can be a good fit for the right Ontario collector car, but it does not replace careful insurance planning. The plate affects your registration status and your permitted use. Your policy controls the protection you have, the value method, the deductible and the claim terms.

    Before your next show, cruise or repair trip, make sure the registration, the intended use and the insurance details all match. If you want help reviewing collector car coverage, contact Lant Insurance to discuss the vehicle and your plans. This article is general information; always rely on the current regulation and your own policy wording for your situation.

    Frequently asked questions

    1. What is a historic vehicle plate in Ontario?

    It is a provincial registration status for a motor vehicle that meets Ontario’s historic vehicle definition. The definition looks at the car’s age, its condition, its permitted road use and whether it has year-of-manufacture plates attached. It is not an insurance product and does not create coverage on its own. Review the current wording in Ontario Regulation 628.

    2. Is a vehicle automatically eligible once it is 30 years old?

    No. The car must be at least 30 years old, but it must also be substantially unchanged or unmodified from the original manufacturer’s product, be used for the permitted purposes, and not have year-of-manufacture plates attached. Age alone is not enough.

    3. Can I use a historic vehicle plate for daily commuting?

    Do not assume so. Ontario’s definition ties highway use to parades, exhibitions, tours or similar automobile club functions, and to repair, testing or demonstration for sale. Regular commuting is not on that list. Check the rule before any trip that does not clearly fit those purposes.

    4. Do I still need auto insurance with historic plates?

    Yes. Ontario requires vehicle owners to carry auto insurance, and drivers must have proof of insurance with them. A historic plate is registration, not proof of insurance. Your car must be properly listed on an active policy. See FSRA’s guide to the insurance requirement.

    5. Will a historic plate automatically lower my premium?

    No. A plate does not create a discount by itself. Pricing depends on factors such as the vehicle, the driving record, the kilometres driven, the coverage selected, the deductible and the insurer. A collector car policy may be priced differently from a regular auto policy, but compare the coverage and the use conditions, not only the premium.

    6. Does a historic plate give my car agreed value coverage?

    No. Agreed value is an insurance arrangement, not a registration benefit. In Ontario it comes from the OPCF 19A endorsement, and it applies only to the vehicle listed on that form. Ask your insurer how the policy settles a total loss, what documents support the value and when the value must be reviewed.

    7. Can a modified classic qualify for historic plates?

    It depends on the changes. The definition requires the vehicle to be substantially unchanged or unmodified from the original manufacturer’s product, so significant modifications may affect eligibility. They should also be disclosed to the insurer, because they can change the car’s value, repair cost and risk profile.

    8. Are historic plates and year-of-manufacture plates the same?

    No. They are separate registration options. Ontario Regulation 628 states that a historic vehicle does not have year-of-manufacture plates attached. If you are considering either one, confirm the current requirements before you choose.

    9. What should I tell my insurer about my historic vehicle?

    Tell the insurer the registration status, the intended use, the estimated annual kilometres, the storage location, the regular drivers, the restoration status and all significant modifications. Provide updated appraisal or restoration records when they affect value. Your policy and premium are based on the facts you give.

    10. Is the annual historic vehicle permit validation fee currently $0?

    Ontario Regulation 628 currently lists a $0 annual permit validation fee for a historic vehicle permit in Schedule 4. This is a registration fee item, not an insurance benefit. Registration rules and fees can change, so confirm the current ServiceOntario process before you apply or renew.

  • Your Pre-Show Checklist: Insurance Edition

    Before you trailer your classic to the next show, cruise-in, or club event, take five minutes to run through this quick coverage check. Most gaps show up here – not on the road.

    Confirm Your Usage Terms Cover the Event

    Some collector policies distinguish between driving to a show and being judged or displayed at one. Check that your policy’s definition of show use covers what you’re actually doing.

    Check Your Mileage Allowance

    Most collector policies cap annual mileage. If you’ve had an active show season, make sure you’re still within your policy’s limit – and let your broker know if you need to adjust it.

    Verify Towing and Transport Coverage

    If you’re trailering your car, confirm your policy covers damage that happens in transit, not just on the road – and that your roadside assistance includes flatbed towing suited to low-clearance vehicles.

    Review Your Agreed Value

    If you’ve done any work on the car since your last appraisal – new paint, mechanical upgrades, interior restoration – your agreed value may be outdated. A quick update now avoids a dispute later.

    Keep Proof of Coverage in the Car

    Some show organizers ask for proof of insurance on-site. Keep a copy of your policy declarations page in the glovebox or on your phone.

    • Usage terms match the event type
    • Mileage is within your annual allowance
    • Transport and towing coverage confirmed
    • Agreed value reflects recent work
    • Proof of insurance on hand

    Questions about your coverage before the next show? Visit our Contact page to reach out.

  • 5 Tips for Getting an Accurate Appraisal on Your Classic Car

    An accurate appraisal is the backbone of an agreed-value policy. If the number is too low, you’re underinsured. If it’s inflated without documentation, a claim can get contested. Here’s how to get it right.

    1. Use a Qualified Collector Car Appraiser

    Not every general appraiser understands classic and collector vehicles. Look for someone with specific experience in your car’s era and market – membership in a recognized appraisal association is a good signal.

    2. Document Originality and Numbers-Matching Status

    Matching numbers on the engine, transmission, and body can significantly affect value. Bring build sheets, title history, and any factory documentation to the appraisal.

    3. Photograph Everything, Including Flaws

    A credible appraisal reflects actual condition – paint, interior, undercarriage, engine bay. Thorough photos protect you if a valuation is ever questioned later.

    4. Keep Restoration and Upgrade Receipts

    Parts invoices, labor records, and shop documentation all support your value and make it easier to update your agreed value after major work.

    5. Reappraise Periodically

    Collector car values shift with the market. Plan to reappraise every 2-3 years, or sooner after a significant restoration, to keep your agreed value current.

    Once you have a solid appraisal in hand, the next step is making sure your policy actually reflects it. That’s where a broker who specializes in collector vehicles earns their keep.

    Get help matching your appraisal to the right policy – visit our Contact page.

  • Agreed Value vs. Actual Cash Value: What Collectors Need to Know

    If you own a classic, muscle car, or restoration project, the single most important line in your insurance policy isn’t the premium – it’s the valuation method. Get this wrong, and a total loss can leave you thousands of dollars short of what your car was actually worth.

    What is Actual Cash Value?

    Standard auto policies use Actual Cash Value (ACV): your vehicle’s value at the time of loss, after depreciation. That works reasonably well for a five-year-old commuter car. It works terribly for a numbers-matching classic, where an adjuster’s depreciation formula has nothing to do with what collectors actually pay for the car.

    What is Agreed Value?

    Agreed Value coverage flips the process. Before the policy is written, you and the insurer agree on your vehicle’s value – typically supported by an appraisal, comparable sales, or documented build costs. If the car is totaled, you’re paid that agreed amount, full stop. No depreciation schedule, no adjuster negotiation, no surprises.

    Why It Matters at Claim Time

    The difference shows up exactly when you can least afford it – after a total loss. With ACV, you’re negotiating your car’s worth with an adjuster during an already stressful moment, often using comparables that don’t reflect condition, originality, or provenance. With Agreed Value, that number was settled months or years earlier, when you had time to document it properly.

    How to Set an Accurate Agreed Value

    • Get a written appraisal from a qualified collector car appraiser
    • Keep receipts and documentation for restoration work and upgrades
    • Reassess value every 2-3 years, or after major work
    • Photograph your vehicle’s condition, including numbers-matching components

    Not every carrier offers Agreed Value coverage, and terms vary – some require periodic reappraisal, others cap coverage relative to appraised value. That’s exactly the kind of detail a broker who specializes in collector vehicles can walk you through before you sign anything.

    Talk to a Lant Insurance broker about agreed-value coverage – visit our Contact page.